PENNSYLVANIA PROPERTY OWNER GUIDES · OCTOBER 2026
An empty house can quietly consume money. Understanding the true annual cost of holding it is the first step toward deciding whether to maintain it, rent it, renovate it, or sell.
- Why vacancy is more expensive than it looks
- Start by calculating the real carrying cost
- Security and insurance should come first
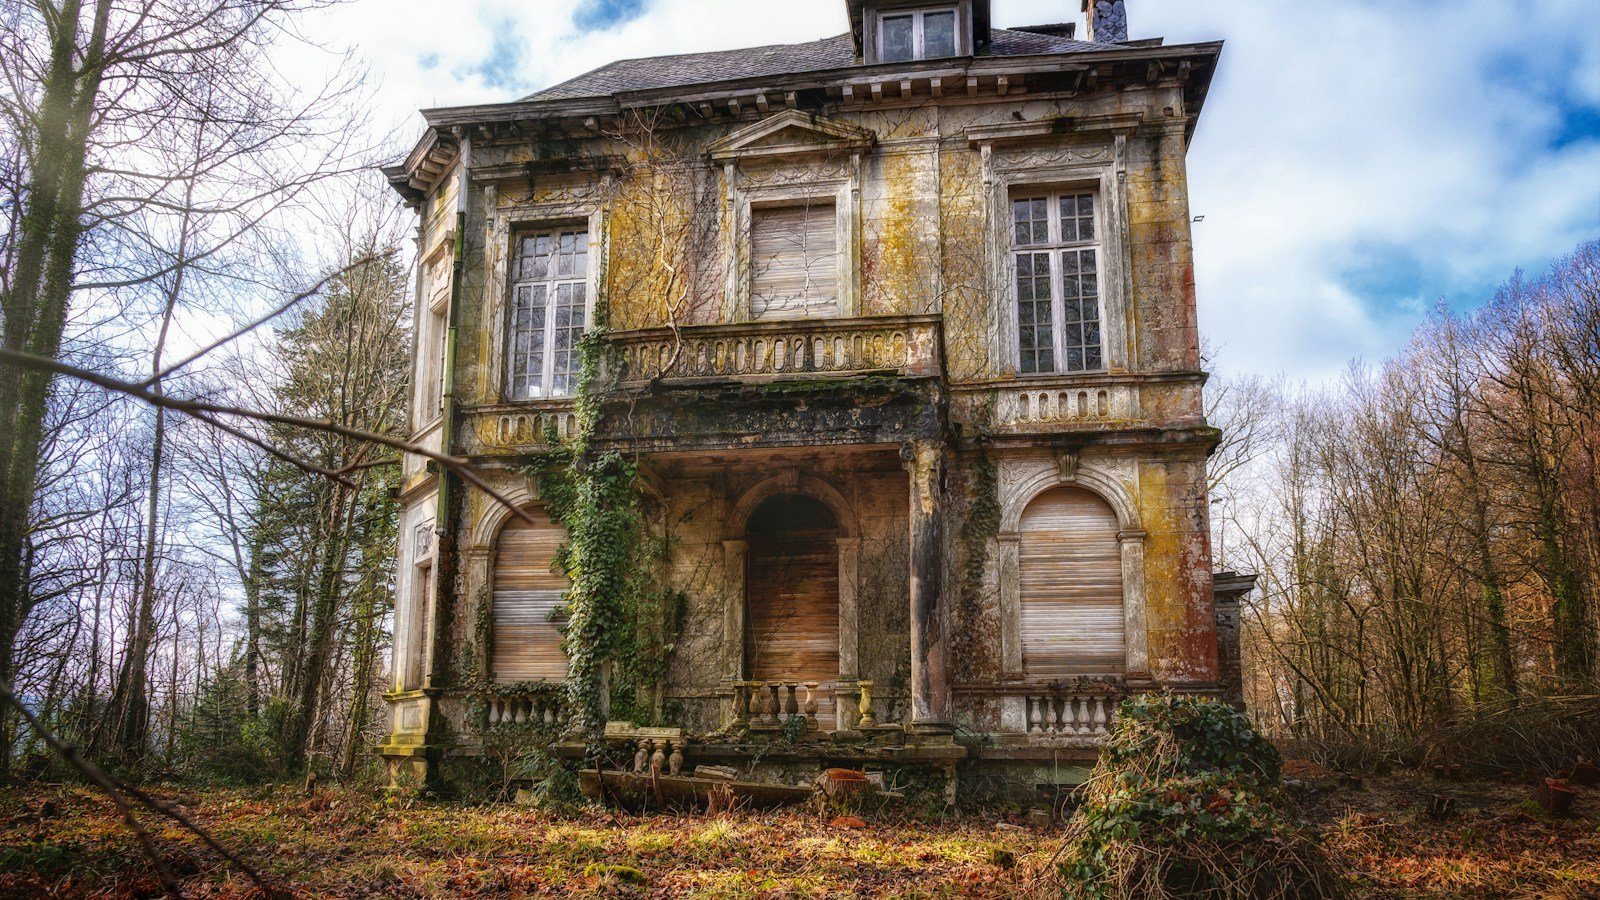
- A vacant home can deteriorate while you decide
- Should you rent the property instead?
- Sell on the open market or approach a direct buyer?
- What to prepare before contacting a buyer
- How VenturePeak handles a property review
Why vacancy is more expensive than it looks
The monthly mortgage payment—if one exists—is only one part of property ownership. A mortgage-free home can still incur county, school, and municipal taxes, insurance premiums, heating expenses, yard care, snow removal, code compliance costs, and repairs. Even small recurring bills add up when nobody is using the property.
A vacant building may also need different insurance coverage. Homeowners should contact their carrier before assuming a regular occupied-home policy remains appropriate. A canceled or limited insurance policy could turn a moderate loss into a much larger one if damage occurs.
Start by calculating the real carrying cost
Write down twelve months of expected taxes, insurance, utilities, landscaping, security, monitoring, and maintenance. Add known repairs that cannot reasonably wait. Then include an allowance for unexpected problems, especially roofs, plumbing, heating, and moisture. Treat these as estimated future costs, not just last year’s bills.
For illustration, if taxes are $2,200, insurance $1,400, utilities $1,500, mowing and snow service $1,000, and repairs $2,500, that’s $8,600 a year before any major surprise. Your actual numbers can be much higher or lower. The purpose is to make an otherwise invisible expense visible.
Security and insurance should come first
Confirm every accessible window and door is secure; arrange reliable check-ins; address obvious water-entry points; and review whether plumbing should be winterized by a qualified professional. Do not shut off heat or utilities without understanding how it affects pipes, safety devices, and insurance terms.
Avoid putting yourself at risk by entering unsafe buildings, basements with water and exposed wiring, or properties with suspected structural instability. Qualified professionals should assess serious hazards. Some municipalities have property-maintenance rules or registration requirements for vacant buildings; check locally.
A vacant home can deteriorate while you decide
Slow leaks can damage plaster, subfloors, and framing before anyone sees them. A small exterior opening can allow water and pests inside. In winter, a failed furnace can lead to frozen pipes. When a home stays empty, there may be nobody to report an issue until the repair has multiplied.
If you inherited the property with relatives, agree who is authorized to make decisions and who covers recurring costs. Document any expenses and keep receipts. It may help prevent disputes when sale proceeds are eventually distributed.
Should you rent the property instead?
A rental may generate income, but an empty home isn’t automatically rent-ready. Budget for habitability and safety concerns, repairs, insurance changes, permits where required, tenant turnover, maintenance, and management. Compare realistic rent to the total operating cost, not merely the tax bill.
If the property requires $30,000 of repairs to rent for $1,100 a month, the investment decision is not as simple as dividing the repair budget by rent. Vacancy allowance, taxes, capital replacements, and tenant-related expenses all matter. A qualified manager or contractor can help estimate what is genuinely necessary.
Sell on the open market or approach a direct buyer?
A traditional listing may create competition and expose the property to owner-occupants or renovation buyers. An as-is investor offer may reduce preparation work and simplify the process, but an investor’s price will usually reflect repair costs and risk. Compare net proceeds after expected expenses, not only the advertised offer.
For vacant properties, access arrangements, utilities, title, taxes, and personal belongings can also affect the timeline. Ask any buyer to explain contingencies and who is responsible for clearing the property. Don’t rely on an informal promise of an unusually fast closing.
What to prepare before contacting a buyer
Have the address, parcel number if known, occupancy status, an honest summary of repairs, a rough tax and utility picture, and information about ownership. Photos can be helpful, but they aren’t required to ask an initial question. If you don’t know the home’s exact condition, say so.
A title company can search for recorded claims during the transaction. The owner should also confirm current taxes and municipal charges with the appropriate authorities. An as-is offer doesn’t make legal or financial obligations disappear.
How VenturePeak handles a property review
VenturePeak considers vacant properties and difficult-to-sell homes. The initial inquiry asks for a small amount of information so we can determine whether a private purchase conversation might be appropriate. We may request an inspection or additional details before discussing terms.
You’re under no obligation to accept a proposal. You may compare a direct sale, traditional listing, rental plan, or continued ownership. The better choice depends on the property and your priorities.
Frequently asked questions
Can I sell a vacant house without cleaning it first? Potentially. Some buyers consider a property and belongings as-is, but the contract must say what happens to personal property.
Does a vacant house require special insurance? Coverage can change after vacancy; ask your insurer about your actual policy.
What if the house has code violations? Confirm the notices, deadlines, and costs with the municipality; disclose relevant information to prospective buyers.
Vacancy after someone moves into assisted living
A home may become empty when a longtime owner downsizes or moves closer to family. In that situation, the household may be balancing care expenses, property upkeep, and emotional attachment. Before selling, confirm who has authority to sign: the owner, a legally authorized agent under a valid power of attorney, or another person recognized under applicable law. A property owner may wish to compare the home’s equity, the cost of maintaining it, and alternatives to a sale with a financial or legal adviser. Avoid rushed commitments and do not assume a family member can act without appropriate documentation.
Why small-town property values require local research
Pennsylvania communities vary enormously. A property in Pottsville or Schuylkill Haven may attract different buyers and rents than a home in Reading, Hazleton, Tamaqua, or a rural township. A broad statewide pricing estimate may miss local demand, street-level condition differences, parking, lot features, and old-building costs. Compare truly similar sales rather than using an online estimate alone. A vacant building in a walkable downtown block may have different prospects from a detached rural house with a septic system. Your decision should reflect the market for that particular address.
Property taxes and municipal charges never take a vacation
An empty home may continue to accumulate real estate taxes, sewer charges, and certain municipal expenses. If bills are going to an old address, owners can fall behind without realizing it. Check the mailing addresses on tax and utility records, request current balances, and keep a central file. If there is an outstanding code-enforcement notice, ask the municipality for the written issue and what would satisfy it. The sooner you identify unresolved charges, the easier it is to estimate sale proceeds and avoid surprises at closing.
Questions that separate a serious offer from a vague promise
Ask whether the interested party is the actual intended buyer, whether proof of funds or financing will be reviewed, and how the property will be evaluated. Request a timeline that accounts for title research, access, and settlement. If you plan to leave furniture or equipment, list it clearly. Check who bears the risk if a previously unknown title issue is found. Be cautious of anyone promising a particular price without seeing even basic condition and ownership information. A reliable proposal should be understandable in writing before you are expected to sign.
A ten-minute vacancy decision worksheet
Write down five numbers: current as-is value estimate, total annual carrying costs, likely immediate repair costs, expected net proceeds from a realistic sale, and your available cash reserve. Next, write down the amount of time you are willing to manage the property. If you cannot comfortably pay to maintain it, that is a reason to evaluate alternatives—but not a reason to accept any price. Review the worksheet with a trusted independent adviser if the property represents most of your savings. VenturePeak can consider an inquiry, but the homeowner’s full financial picture should guide the final decision.
When should you recheck the decision?
If you choose to keep the house for now, set a clear review date rather than letting months pass without a plan. Review insurance, taxes, property condition, maintenance invoices, and local comparable sales quarterly. If repairs become urgent or the market changes, update your numbers. A property that seemed reasonable to hold in spring may carry very different winter costs. You can also ask a qualified local professional for a fresh valuation and revisit rental feasibility. An informed owner can choose to hold, improve, or sell without relying on an emergency to force the decision.
Want to discuss your property’s options?
Tell VenturePeak about your property. We will review the information and contact you to discuss whether a direct purchase could be a fit. No obligation to accept an offer.
Official resources and further reading
- Pennsylvania Local Government Commission — municipal codes
- Pennsylvania residential seller disclosures
Educational information only, not legal, financial, or tax advice. VenturePeak may purchase property as a principal. Seek independent qualified advice for your situation.